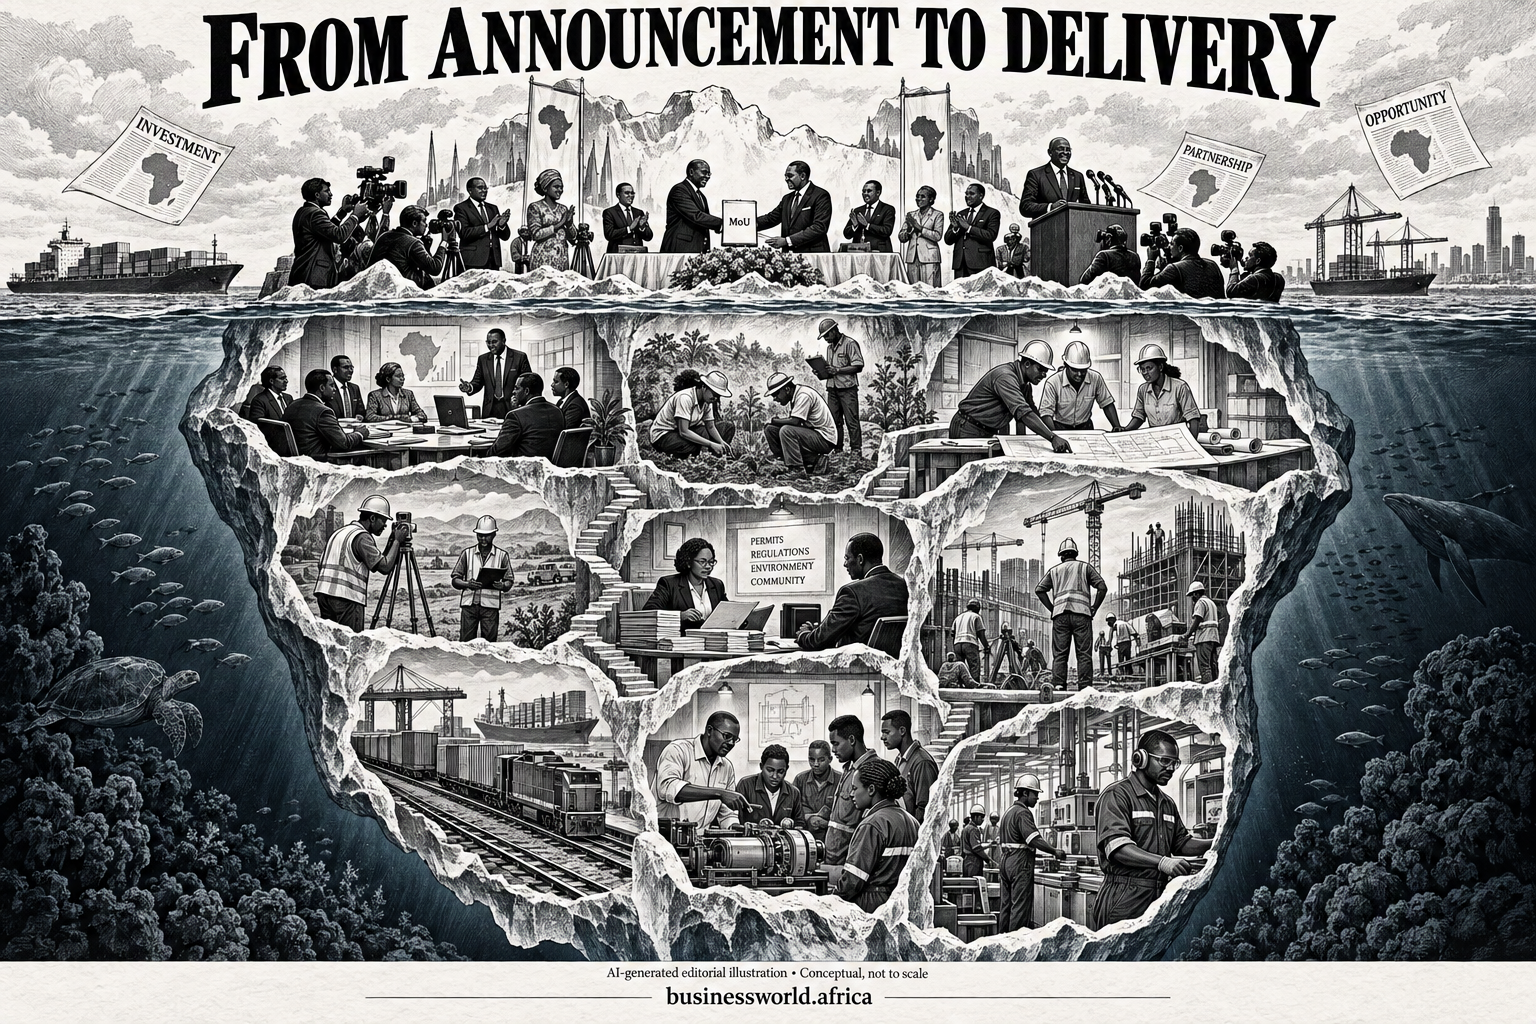
Figure 1: Cover illustration. AI-generated editorial illustration created for BusinessWorld.Africa. The artwork conceptually represents the gap between investment announcements and actual project implementation. All investment figures, project descriptions and implementation statuses depicted are fictional and do not refer to specific real-world projects or verified outcomes.
African governments are increasingly celebrating multibillion-dollar foreign investment commitments. But announcements are not assets, pledges are not capital expenditure, and projected jobs are not people earning salaries. It is time to measure investment by what it delivers, not what it promises.
There is something almost predictable about the way investment announcements are celebrated across Africa.
A foreign technology company announces plans to invest $1 billion in a data centre. A government secures a $5 billion infrastructure partnership. An international energy company commits billions of dollars to an oil and gas development. A foreign consortium expresses interest in building a railway, industrial park or manufacturing facility.
The announcement makes headlines. Government officials describe it as evidence of investor confidence. Investment agencies celebrate their success in attracting international capital. Politicians highlight projected employment figures, expected contributions to GDP and infrastructure that will supposedly transform the economy.
Sometimes, the figures are presented almost as though the money has already entered the country.
But there is a fundamental question that rarely receives the same attention as the announcement itself: What happens after the cameras leave, the press releases are published and the visiting investors return home?
Does the money arrive? Does construction begin? Are factories completed? Does the infrastructure become operational? Are the promised jobs created? And how many of those jobs go to local workers?
These are not simply questions of journalistic scrutiny. They concern how African economies measure economic progress and evaluate their success in attracting foreign direct investment (FDI).
Foreign investment is important to Africa’s development. The continent needs capital to close infrastructure gaps, expand manufacturing, improve energy access, modernise transportation networks and create productive employment. Domestic savings and public budgets alone are unlikely to finance the scale of investment required.
However, attracting investors and converting their intentions into economic outcomes are two different achievements.
Africa’s investment narrative needs to move beyond the size of announcements and examine what actually gets delivered.
The difference between investment announcements and actual investment
One of the biggest problems with investment reporting is that fundamentally different financial activities are frequently presented under the same umbrella.
A company announcing that it intends to invest $2 billion in an African country is not the same as transferring $2 billion into that economy. A government signing a memorandum of understanding with an international consortium does not mean the consortium has secured financing. Similarly, an investor receiving approval to develop a project does not necessarily mean construction has started.
There are several stages between an investment announcement and actual economic impact:
- Investment interest: A company expresses interest in entering a market or exploring an opportunity.
- Investment commitment: The company publicly announces an intended investment, often with an estimated value.
- Financial commitment: Financing is secured, contracts are signed and the project moves towards implementation.
- Capital deployment: Money is actually spent on construction, equipment, technology and other project requirements.
- Operational delivery: The facility is completed, begins operating, generates economic activity and creates employment.
These stages should never be treated as interchangeable.
A memorandum of understanding is not a factory. A groundbreaking ceremony is not a completed industrial facility. A projected 10,000 jobs is not evidence that 10,000 people have been employed.
This distinction is important because investment announcements are widely used to communicate economic progress, even when the figures represent intentions rather than completed financial transactions.
Research by the McKinsey Global Institute highlights the limitations of interpreting announced investment figures as actual capital deployed. Projects can change in scope, be delayed or never materialise.
The implication is straightforward: an announced dollar is not necessarily a dollar spent.
What do Africa’s investment figures actually tell us?
Africa’s recent foreign investment figures illustrate why greater scrutiny is necessary.
According to UN Trade and Development (UNCTAD), foreign direct investment inflows to Africa increased by 75 per cent to a record $97 billion in 2024.
On the surface, this was an extraordinary achievement. However, a substantial portion of the increase came from a single major international project finance transaction associated with Egypt’s Ras El-Hekma development.
Excluding that transaction, African FDI inflows increased by approximately 12 per cent to $62 billion.
There was another important development in the same report: the value of announced greenfield investments in Africa fell by 37 per cent, from $178 billion in 2023 to $113 billion in 2024.
This creates an interesting contrast. The continent recorded a historic increase in FDI inflows, yet the value of newly announced greenfield projects declined considerably.
Why does this matter?
Because FDI inflows and announced greenfield projects measure different things. FDI statistics record cross-border investment transactions, including equity, reinvested earnings and certain intercompany debt. Greenfield announcements track proposed new facilities and expansions.
An increase in one does not automatically mean an equivalent increase in new factories, productive capacity or employment.
The geographical distribution of investment also matters. UNCTAD reported that West Africa’s FDI inflows declined by 7 per cent in 2024, while the value of announced greenfield investments in the subregion fell by 83 per cent.
Nigeria, the region’s largest economy, recorded a 42 per cent decline in FDI inflows.
These figures challenge the tendency to interpret continental investment headlines as evidence that every African economy is experiencing the same investment recovery.
The continent’s investment performance remains concentrated in particular countries, sectors and exceptionally large transactions.
The more important question is whether these investments are creating a sufficiently broad foundation for industrialisation and employment.
The World Bank’s warning: Many announced projects never reach completion
Perhaps the strongest evidence for taking the implementation question seriously comes from research published by the World Bank in 2026.
In its Policy Research Working Paper, From Announcement to Completion: Tracking Big FDI Projects in LICs, researchers examined large greenfield foreign investment projects announced in low-income countries between 2011 and 2020.
Their finding deserves attention: fewer than half of the projects in their sample were completed or remained on track.
The researchers identified several obstacles to implementation, including policy uncertainty, regulatory difficulties, financing constraints, administrative challenges and changing economic conditions.
They also found that larger projects were less likely to reach completion and that completed projects took an average of approximately three years to move from announcement to operation.
The study covers low-income countries globally, not Africa alone. Its findings should therefore not be presented as an Africa-specific failure rate. Nevertheless, it provides empirical evidence that the implementation gap is a genuine development challenge.
The research raises an uncomfortable question for African investment agencies: if so many large announced projects struggle to reach completion, why do governments continue celebrating investment commitments without publishing equally prominent implementation reports?
The full study is available through the World Bank’s Policy Research Working Paper series.
South Africa: When investment pledges meet the delivery question
South Africa offers one of the clearest examples of the difference between investment commitments and actual economic delivery.
The country’s Presidential Investment Conference, established in 2018, has become an important platform for attracting domestic and international investment.
At its sixth investment conference in March 2026, the country secured 81 investment commitments worth approximately R889.8 billion.
However, the more interesting figure came from the implementation record of the earlier investment drive.
According to Reuters’ April 2026 reporting, approximately R1.5 trillion in pledges accumulated since 2018 had resulted in R634 billion entering the economy by March 2026.
That represents just under 42 per cent of the earlier pledged amount.
It is important to understand what this figure means. It does not mean that the remaining 58 per cent has necessarily been cancelled. Some projects may still be under construction, awaiting approvals or progressing through financing arrangements.
South Africa’s official Presidential Investment Drive tracker provides further implementation information, including completed projects and those still under construction.
This is a more useful way of discussing investment than simply announcing another multibillion-rand target.
It allows citizens to distinguish between projects that have been completed, those being implemented and those still awaiting delivery.
South Africa’s experience also demonstrates why a country can attract impressive investment commitments without immediately resolving its unemployment and infrastructure challenges.
Investment announcements cannot independently resolve electricity constraints, transport difficulties, high unemployment and weak economic growth. Projects must be implemented, and the broader business environment must allow them to operate profitably.
Kenya: The $1 billion data centre and the distance between an announcement and construction
In May 2024, Microsoft and UAE-based artificial intelligence company G42 announced plans to invest approximately $1 billion in a data centre project in Kenya.
The proposed facility was expected to strengthen the country’s position as a regional digital infrastructure hub, expand access to cloud computing and support artificial intelligence development.
However, the subsequent implementation process demonstrated that a large corporate commitment does not automatically translate into construction.
In May 2026, Business Daily Africa reported disagreements between Microsoft and the Kenyan government over the proposed facility. Issues included government guarantees for demand and regional cloud capacity, connectivity and electricity requirements.
The disagreements had delayed construction.
The case illustrates an important reality: the project required more than an investor willing to spend money. It required agreement on commercial arrangements, electricity supply, regional demand and government obligations.
Kenya had successfully attracted international interest, but still needed to resolve the conditions necessary to turn that interest into an operational facility.
There is, however, another development worth considering.
In September 2025, the Kenyan government announced the groundbreaking of Airtel Africa’s Nxtra data centre at Tatu City. According to the Ministry of Information, Communications and the Digital Economy, the facility was planned to have a capacity of 44 megawatts, with completion targeted for the first quarter of 2027.
These two projects demonstrate why investment reporting should track individual developments rather than treat every announcement as either a success or a failure.
The Microsoft-G42 project encountered implementation difficulties, while the Nxtra project had progressed to groundbreaking. Neither announcement alone establishes the final employment or infrastructure impact.
Mozambique: What happens when a multibillion-dollar investment is suspended?
Mozambique offers another important example of the risks associated with large foreign investments.
The Mozambique LNG project, led by French energy company TotalEnergies, is one of Africa’s most significant energy investments.
Estimated at approximately $20 billion, the project was expected to transform Mozambique into a major global liquefied natural gas producer.
However, the project was suspended in 2021 after an insurgency in Cabo Delgado created serious security concerns. Construction activities stopped, workers lost employment opportunities and local businesses lost expected contracts.
The development became a reminder of how vulnerable large investments can be to security and political risks.
There was, however, a significant development in 2026.
On 29 January, TotalEnergies announced the full resumption of onshore and offshore activities following the lifting of force majeure in November 2025.
According to the company’s official announcement, more than 4,000 workers had been mobilised, including over 3,000 Mozambican nationals.
The company expects the project to create up to 7,000 direct jobs for Mozambicans during construction. It also expects contracts awarded to Mozambican companies to exceed $4 billion. First LNG production is expected in 2029.
This is an important distinction between a project that has been abandoned and one that has experienced significant delays before resuming.
It would be inaccurate to describe Mozambique LNG as a failed investment. Construction has resumed and workers have returned.
But it would be equally inaccurate to count all its projected employment and economic benefits as already delivered.
The 4,000 workers mobilised represent a reported current workforce. The 7,000 jobs are a projected construction-phase figure. The expected local contracts are not equivalent to money already received by Mozambican businesses.
The project still needs to reach commercial production.
Nigeria’s investment paradox: More capital, but how much productive investment?
Nigeria offers an especially interesting case because the country has spent considerable time trying to reposition itself as an attractive destination for foreign investors.
Yet its investment figures reveal why it is important to distinguish between different forms of capital.
According to figures reported by Reuters in March 2026, Nigeria’s capital inflows increased by 90 per cent to $23.22 billion in 2025, compared with $12.32 billion in 2024.
At first glance, this appears to be an impressive recovery.
However, foreign portfolio investment accounted for approximately $19.74 billion, representing around 85 per cent of total capital importation. Foreign direct investment increased only modestly, from $675 million in 2024 to $923 million in 2025.
This distinction matters.
Portfolio investors purchase financial assets such as bonds and shares. They can improve access to financing and support financial markets.
FDI, on the other hand, generally involves a lasting interest and significant influence in an enterprise in another economy.
Neither category is inherently unimportant. But they have different implications for long-term productive investment.
A foreign investor purchasing Nigerian government bonds is not necessarily financing a new factory. An international fund buying bank shares is not necessarily constructing additional industrial infrastructure.
Nigeria’s capital importation figures should therefore not be interpreted as $23.22 billion of new factories, roads, manufacturing facilities and employment opportunities.
The country needs investment in electricity, agricultural processing, transportation, industrial production, technology and other productive sectors.
The challenge is not merely attracting foreign money. It is attracting more long-term capital that finances productive enterprises, expands infrastructure and creates sustainable employment.
The Reuters report on Nigeria’s 2025 capital inflows provides an important starting point for understanding this distinction.
Do foreign investments actually create the promised jobs?
Investment announcements frequently come with impressive employment projections.
A company announces a manufacturing facility and promises 5,000 jobs. An energy project advertises thousands of construction opportunities. A technology investment is expected to create employment for engineers, technicians and digital professionals.
But projected employment is not necessarily the number of jobs that will eventually exist.
There are three important distinctions.
Construction jobs versus permanent jobs. A major infrastructure project may employ thousands of workers during construction. However, once the facility becomes operational, its permanent workforce may be considerably smaller.
Direct versus indirect employment. A foreign-owned factory may employ 500 people directly while generating additional opportunities for logistics companies, suppliers and domestic businesses. These indirect effects can be substantial, but they should be measured rather than assumed.
Projected versus verified employment. A company estimating that a project will create 10,000 jobs is not the same as having 10,000 people on its payroll.
A 2024 academic study, Greenfield FDI and Job Creation in Africa, examined greenfield investment projects across the continent between 2013 and 2020.
The researchers found that direct employment from greenfield investment could contribute to formal job creation in manufacturing and services. However, these jobs represented a relatively small proportion of total employment creation.
They also identified a significant data limitation: employment figures for approximately 91 per cent of the projects in the commercial databases examined were estimated rather than directly reported.
This does not mean the announced jobs were fictitious. It means that a substantial proportion of the figures used to describe investment employment potential were statistical estimates rather than verified payroll records.
That distinction deserves far more attention in African economic reporting.
When a government announces that a foreign investment will create 20,000 jobs, journalists should ask whether those jobs are based on an actual workforce, an investor’s projection or a statistical estimate.
Investment must also benefit domestic businesses
There is another issue that deserves greater attention: the extent to which foreign investment integrates into the domestic economy.
A foreign company can establish a large industrial facility, generate substantial revenue and employ people without necessarily creating extensive opportunities for domestic businesses.
This can happen when most of its machinery, raw materials, technical services and specialised personnel are sourced from outside the country.
The investment may still generate taxes, wages and exports. However, its wider economic contribution will be stronger when domestic businesses participate in the supply chain.
For example, a foreign automotive manufacturer establishing an assembly plant could create opportunities for local producers of vehicle components, packaging materials, logistics services and maintenance.
Similarly, an international agricultural investment could support domestic farmers, food processors, storage operators, transport companies and distributors.
Africa cannot build sustainable manufacturing economies if foreign investment remains concentrated in isolated projects with limited connections to domestic enterprises.
Governments should therefore assess investment proposals not only by the capital involved but also by their potential to develop local supply chains, transfer technology, improve workforce capabilities and strengthen domestic productive capacity.
What African governments should start measuring
Investment conferences are not inherently problematic. They provide opportunities for governments to engage investors, showcase commercial opportunities and negotiate partnerships.
The problem is the disproportionate emphasis on investment commitments, with much less attention given to what happens afterwards.
A government might announce $10 billion in investment commitments and 50,000 projected jobs. But how much financing has been secured? How much capital has actually been deployed? How many projects have commenced? How many people have been employed?
Governments and investment promotion agencies should establish publicly accessible investment delivery trackers.
These should monitor:
- Announced investment: The original value and date of each commitment.
- Financing secured: How much funding has been formally arranged.
- Capital deployed: How much money has actually been spent.
- Project implementation: Whether the project is awaiting approval, under construction or operational.
- Employment: Actual direct jobs created, distinguishing temporary from permanent employment.
- Local participation: The number of local workers and domestic businesses involved.
- Infrastructure delivered: Physical assets completed and made operational.
- Economic contribution: Production, exports, taxes, local procurement and productivity.
The information should be updated periodically, preferably quarterly or annually.
Governments should also distinguish between foreign and domestic investment, portfolio investment, grants, loans and equity transactions. Each has a different financial structure and economic implication.
Consider the difference between two possible government statements:
“We have secured $10 billion in investment commitments, expected to create 50,000 jobs.”
And:
“Of the $10 billion announced in previous investment commitments, $4 billion has been deployed across 18 projects. Seven projects are operational, six are under construction and five remain at the financing or approval stage. The completed projects have created 3,200 verified direct jobs.”
The second statement is less spectacular, but considerably more useful.
It provides an indication of actual progress and gives the public something against which future performance can be measured.
Conclusion: Africa needs investment delivery, not investment theatre
The question is not whether foreign investment announcements translate into actual jobs and infrastructure.
Some do. Others are delayed, reduced, suspended or abandoned. Still others produce genuine economic benefits that differ considerably from the expectations initially communicated.
The problem is that African countries have not consistently developed the public accountability systems needed to distinguish between these outcomes.
The continent should be more ambitious about how it measures investment success.
A $10 billion announcement may generate international attention, but a completed $500 million manufacturing facility employing thousands of local workers, sourcing from domestic suppliers and producing goods for export may deliver far more tangible development benefits.
The size of the announcement matters less than the quality, implementation and long-term economic contribution of the investment.
Africa does not simply need more investors willing to announce billions of dollars.
It needs investors willing to build, governments capable of facilitating delivery, domestic businesses equipped to participate and institutions committed to measuring results.
For African media organisations, this also presents an important opportunity to improve economic journalism. Instead of publishing another headline about a foreign company promising to invest $2 billion, journalists should return six months or a year later and investigate whether the project has progressed.
They should establish whether construction has started, whether workers have been recruited, whether local businesses have received contracts and whether the promised infrastructure is operational.
Where projects have stalled, the reasons should be investigated. Where they have succeeded, the actual economic benefits should be documented.
Investment journalism should not end when the announcement is made. That is where the more important reporting begins.
The next measure of Africa’s investment success should not be how much money its leaders can announce, but how much of that money actually reaches the economy, what it builds, whom it employs and what remains when the headlines disappear.
Sources and further reading
- UNCTAD – Africa: Foreign Investment Hit Record High in 2024.
- UNCTAD – World Investment Report 2025: Regional Trends in Africa.
- World Bank – From Announcement to Completion: Tracking Big FDI Projects in LICs.
- Greenfield FDI and Job Creation in Africa.
- Reuters – South Africa’s Investment Pledges and Delivery Gap.
- InvestSA – Presidential Investment Drive.
- Business Daily Africa – Kenya and Microsoft’s Data Centre Disagreement.
- Kenya Ministry of ICT – Nxtra Data Centre Groundbreaking.
- TotalEnergies – Mozambique LNG Project Resumption.
- Reuters – Nigeria’s Capital Inflows Jump 90% in 2025.
- McKinsey Global Institute – The FDI Shake-up.
- African Development Bank – African Economic Outlook.